Behind on Your Colorado Springs Mortgage? The El Paso County Foreclosure Calendar and a Cash Sale
Facing foreclosure in Colorado Springs? How the El Paso County Public Trustee calendar works (NED, 110–125 days to a Wednesday sale, cure deadline, Rule 120), why owners can't redeem after the sale, and when a pre-sale as-is cash offer makes sense. Call (405) 622-8705.
Short answer: In Colorado Springs, the El Paso County Public Trustee runs the foreclosure, and a residential auction is set 110 to 125 days after the lender’s Notice of Election and Demand is recorded. You can still sell as-is for cash until that Wednesday sale, but Colorado owners can’t buy the house back afterward, so the whole question is whether a closing fits before the auction date. A cash offer is a comparison number, not a way to stop the process.
By HomeCashOffer Team. Local selling basics for the metro live in our Colorado Springs hub and Colorado Springs city page.
What does the El Paso County foreclosure calendar actually look like?
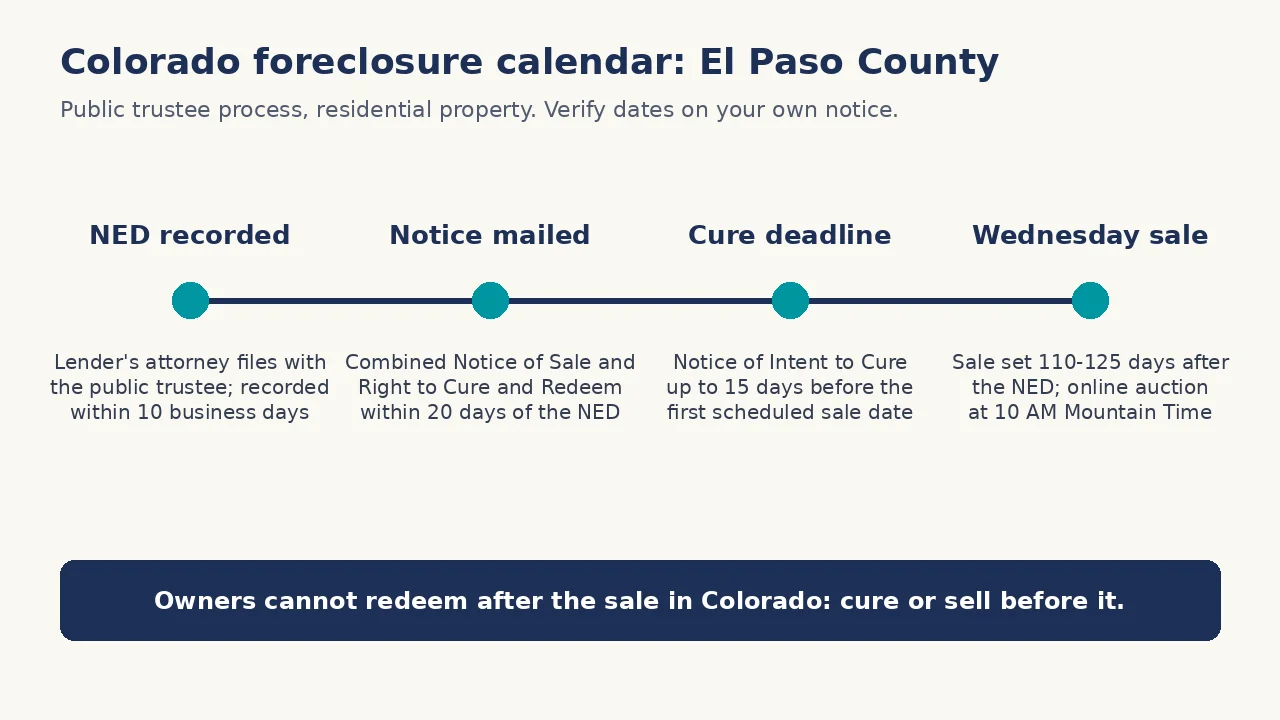
It starts when the lender’s attorney files with the public trustee, not with a lawsuit. The El Paso County Public Trustee says the filing must come from a Colorado-licensed attorney for the lender, include the evidence of debt and deed of trust, and carry a deposit of $800 (or an ACH agreement). The office then rejects the filing or records the Notice of Election and Demand, or NED, within ten business days. Recording the NED starts the clock.
From there, the same office says:
- A Combined Notice of Sale and Right to Cure and Redeem goes to the people on the mailing list no more than 20 calendar days after the NED is recorded.
- That notice is mailed again 45 to 60 days before the first scheduled sale date, and published for five consecutive weekly publications.
- The sale date lands 110 to 125 calendar days after recording for residential property.
- Auctions run online on Wednesdays at 10:00 AM Mountain Time, and the winning bidder must tender cash or certified funds for the full amount.
If you got a letter from a Colorado law firm instead of a court summons, that’s normal here: the public trustee process is out-of-court until the Rule 120 step below.
Why is the cure deadline the date that matters most?
Because Colorado gives you a window before the sale and nothing after it. Arapahoe County’s published foreclosure timeline lays out how it works: the owner may file a Notice of Intent to Cure up to 15 calendar days before the first scheduled sale date, the trustee asks the lender for a cure statement, and the owner must pay by the statement’s expiration or by noon on the Tuesday before the Wednesday sale, whichever comes first. El Paso County’s own right-to-cure page was timing out when we checked, so confirm your exact figures with the El Paso office.
Two practical points follow:
- A cure figure is not just missed payments. It includes the interest, late charges, fees and costs the lender’s attorney has added, which is why it can look much bigger than the number on your last statement.
- If you plan to sell instead, that same 15-day mark is a useful working deadline for having a signed contract and a title company ready to wire a payoff.
What happens at the Rule 120 hearing?
It’s the court’s check that the sale is proper, and it’s narrower than most owners expect. The Colorado Judicial Branch explains that the lender asks the district court in the county where the house sits for an order authorizing the sale. You have until seven days before the hearing date to file a response; if you don’t, the order is entered even if you show up. The court only reviews whether there’s a reasonable probability a default occurred and whether an order is proper, and the Judicial Branch says plainly that it does not weigh whether you were out of work.
The Colorado Bar’s summary of the revised Rule 120 adds that the scope can include Servicemembers Civil Relief Act compliance, whether the moving party is the real party in interest, and whether a pending loan-modification request bars the sale as a matter of law. That SCRA piece matters in a city where, per Census data, 52,224 residents were veterans in 2020–2024.
You don’t have to move out when you get the notice, and the Judicial Branch says you generally stay until the sale and deed happen. That’s not a reason to ignore the calendar.
Can the lender still sue me after the auction?
Yes, a deficiency claim is possible. A summary of C.R.S. § 38-38-106 says the lender’s bid must be at least its good-faith estimate of fair market value (less senior liens, unpaid taxes and holding and selling costs), but a lender’s failure to meet that doesn’t invalidate the sale; it’s a defense for the person sued. Read the statute with a Colorado attorney, because that summary isn’t a substitute for the text.
The second shock is tax. IRS Publication 4681 says the federal exclusion for canceled debt on a main home doesn’t apply to discharges after 2025 unless they come under a written agreement made before 2026. A short sale or deed in lieu that ends in forgiven debt can produce a 1099-C. A sale that pays the mortgage in full creates none.
Does a Colorado Springs house usually have equity to sell into?
Often there’s something to work with, but check your own payoff. Census QuickFacts shows the city’s median value of owner-occupied homes at $452,600 (2020–2024) and median owner costs with a mortgage at $2,063 a month, against a median household income of $84,818. The owner-occupied rate was 60.9%, and the city’s population estimate for July 1, 2025 was 494,743.
Those are medians for the whole city. A 1970s ranch off Powers Boulevard, a townhome near Briargate and a foothills house sit in different places. What matters is the gap between your payoff and what a buyer pays as-is:
- Payoff well under value. A sale can leave you cash after payoff, back interest and closing costs. Compare an as-is cash number with a listing net using our cash offer vs. listing guide.
- Payoff near value. Costs eat most of the margin; ask the servicer early about a short sale.
- Payoff above value. The lender must approve any sale, and a cash buyer can’t waive that.
Will fire history make a Pikes Peak-area house harder to sell?
It can, mainly through insurance and buyer questions. The Gazette’s disaster statistics record 347 homes destroyed in the 2012 Waldo Canyon fire with an insured loss above $453 million, and 488 homes destroyed in the 2013 Black Forest fire with an insured loss above $292 million. The Colorado Springs Pioneers Museum’s account places the Waldo Canyon deaths in Mountain Shadows. A house in or near the wildland-urban edge may need a current insurance quote before a conventional buyer’s lender will move, and that delay is a real cost when you’re counting days to a Wednesday auction.
If you’ve fallen behind partly because insurance premiums or repairs piled up, say so when you ask for offers. It changes how a buyer prices the house.
How does a pre-sale cash closing work on this calendar?
Think backward from the Wednesday sale date on your notice.
- Get two written numbers from the servicer: a payoff good through a few days past your target closing, and the reinstatement or cure figure.
- Open title now. Second mortgages, HOA balances, unpaid contractor liens and an unrecorded divorce transfer are what delay closings.
- Sign a contract with a closing date well ahead of the auction, and send it to the servicer’s foreclosure attorney. Whether to pause is their call.
- Close through a Colorado title company or attorney so the payoff wires straight to the servicer and the release gets recorded. Once the public trustee sells the house, the owner’s chance to cure is gone.
- Keep the federal timeline in mind. Under Regulation X, a servicer generally can’t make the first foreclosure filing until a loan is more than 120 days delinquent, and a complete loss-mitigation application received early enough can limit when the sale proceeds. If you still want to keep the house, apply early.
From our deals
When foreclosure-calendar sellers come to us, the problem is usually the timeline, not the price. Someone sends a notice, a mortgage statement and a few phone photos, and wants to know whether a closing can fit. We tell them what we need to see, say plainly when the date is too close, and don’t promise to beat an auction. The sellers we can help most are the ones who call early enough for title to be clean before the cure deadline, and sometimes the honest answer is to call a housing counselor first.
How do I spot a foreclosure-rescue scam here?
A recorded NED puts your name on mailing lists, so expect letters, texts and door-knockers. Be wary of anyone who:
- guarantees they can save the house,
- asks you to sign over the deed “temporarily,”
- charges an upfront fee for a loan modification,
- tells you to stop talking to your servicer, or
- wants your payment sent to them.
The Colorado Judicial Branch lists the Colorado Attorney General’s Mortgage Fraud Information Center at (800) 222-4500 for complaints. A legitimate purchase has a written contract, a title company or attorney, and a payoff that goes to your servicer, not to the buyer.
Who can help if I want to keep the house?
Start with free help. The Colorado Foreclosure Hotline is (877) 601-4673, per the Colorado Judicial Branch, which also points to Colorado Legal Services and local housing authorities. A housing counselor can walk you through loss mitigation, and an attorney can read your Rule 120 notice and tell you what a response should say.
We’re a home buyer. We aren’t a counselor or a law firm, and we can’t stop a foreclosure.
When is a cash sale the wrong move?
Skip it when:
- The hardship is temporary and a repayment plan, modification or family help can bring you current.
- You have real equity and months left on the calendar. A listing may net more once you add up realistic carrying costs.
- You owe more than the house is worth. That’s short-sale territory and the lender approves it.
- You’re considering bankruptcy. Talk to a Colorado bankruptcy attorney before signing a purchase contract.
- Co-owners or heirs disagree. Everyone on title has to sign, and a cash number doesn’t change that.
For other state calendars, see Nashville’s trustee sale, Atlanta’s first-Tuesday sale, and our foreclosure timelines by state. If the house needs work before any buyer will touch it, see selling as-is in Denver.
What does asking HomeCashOffer for an offer involve?
You send the address, the sale date on your notice, who lives there and its condition. We give a written as-is cash offer with proposed terms; you take it to your attorney and title company. No cleanout, no repairs, no showings. Asking for an offer doesn’t pause the public trustee’s calendar and doesn’t obligate you.
Call (405) 622-8705 or request a cash offer online. Have your Notice of Election and Demand paperwork and latest mortgage statement ready.
HomeCashOffer, 3000 W Memorial Rd, Ste 123 Unit 308, Oklahoma City, OK 73120. (405) 622-8705. We are not a lender, housing counselor or law firm, and we cannot stop a foreclosure.
Related reading: Sell my house fast in Colorado Springs · Colorado Springs, CO city page · Cash offer vs. listing · What to expect from a cash offer · Foreclosure timelines by state
Sell your house fast in these markets
Local cash offer pages—or start with a nationwide request.
Frequently asked questions
How long do I have from the first foreclosure filing to the Colorado Springs auction?
For residential property, the El Paso County Public Trustee sets the sale date no fewer than 110 and no more than 125 calendar days after the Notice of Election and Demand is recorded. The lender's attorney files the paperwork, and the public trustee records it within ten business days of receiving it. Your own notice shows the actual date, so read it first.
Can I still sell my house after the Notice of Election and Demand is recorded?
Yes. You stay the owner until the public trustee's sale is complete. A sale that closes and pays the lender before the auction date can end the foreclosure, but title work, payoff letters and a signed contract all have to line up inside the calendar. Colorado owners don't get a second chance after the auction, so the closing date matters more than the offer price.
Do I have a right to buy my house back after a Colorado foreclosure sale?
No. For foreclosures under current law, owners cure before the sale rather than redeem after it. Only qualifying junior lienholders can redeem, by filing an intent to redeem within eight business days of the sale. The Colorado Supreme Court restated that distinction in Oakwood Holdings v. Mortgage Investments Enterprises (2018).
What is a Rule 120 hearing, and can I stop the foreclosure with it?
It's the court step where the lender asks the district court for an order authorizing the sale. The court looks at a narrow set of questions, such as whether there's a reasonable probability of default and Servicemembers Civil Relief Act compliance. You can file a response up to seven days before the hearing date; if you don't, the order can be entered even if you show up. Hardship alone isn't something the judge weighs, so talk to a Colorado attorney early.
Can the lender still pursue me if the sale doesn't cover the loan?
It can. C.R.S. § 38-38-106 allows a deficiency claim, and the lender must bid at least its good-faith estimate of the property's fair market value less senior liens, taxes and holding costs. If you owe more than the house will bring, ask an attorney about a short sale or deed in lieu before the sale date, and ask a tax professional whether canceled debt could create a 1099-C.
Where can I get free help in Colorado if I want to keep the house?
The Colorado Foreclosure Hotline at (877) 601-4673 is listed by the Colorado Judicial Branch. The Colorado Attorney General's Mortgage Fraud Information Center, (800) 222-4500, takes reports about foreclosure-rescue and loan-modification scams. HomeCashOffer is a home buyer, not a counselor, and we'll say so if a counselor is the better first call.
Ready to see what a cash offer looks like?
No repairs required. No agent commissions when you sell to us. No obligation to accept.
Request your no-obligation cash offer
Prefer a dedicated form? Visit Get a Cash Offer Today.
Get My Cash Offer
Share your name, phone, and property address. No obligation. We will follow up shortly.