Behind on Payments in Houston, TX? Reading the Texas Foreclosure Calendar Before You Sell
Behind on your Houston mortgage? How the Texas 20-day cure letter, 21-day notice of sale and first-Tuesday auction at Harris County's Bayou City Event Center work, how home equity, HOA and tax liens run on different clocks, what the Houston market says about listing on a deadline, and when a cash sale is the wrong move. Call (405) 622-8705.
Short answer: Yes, you can usually sell a Houston house while you’re behind on payments, right up to the first-Tuesday trustee sale, if the sale pays off the loan and other liens at closing. In Texas the timing comes down to two letters: a notice of default that must give a homeowner at least 20 days to cure, and a notice of trustee sale that must come at least 21 days before the auction. Which of those you have in hand tells you whether there’s time to list or whether only a fast, certain closing can beat the date.
Picture a brick ranch in Alief or Spring Branch, or a newer two-story in a Cypress or Katy subdivision with a homeowners association and a MUD line on the tax bill. The payment was fine until the insurance renewal came in high, the escrow account ran short, and the servicer raised the monthly payment to catch up. Then came a layoff, a medical bill or a divorce, and two missed payments became four. Now there’s a certified envelope on the counter.
This guide explains what that Texas paperwork means, how the Harris County calendar works, which kind of lien you’re dealing with, and how to choose between catching up, listing and a direct cash sale. If you already want numbers, start on the Houston city page.
Which letter did you get, and how much time does it leave?
The letter’s title tells you roughly where you are. Texas runs most home foreclosures outside court, under the power of sale in your deed of trust, and Texas Property Code Chapter 51 sets the order of events:
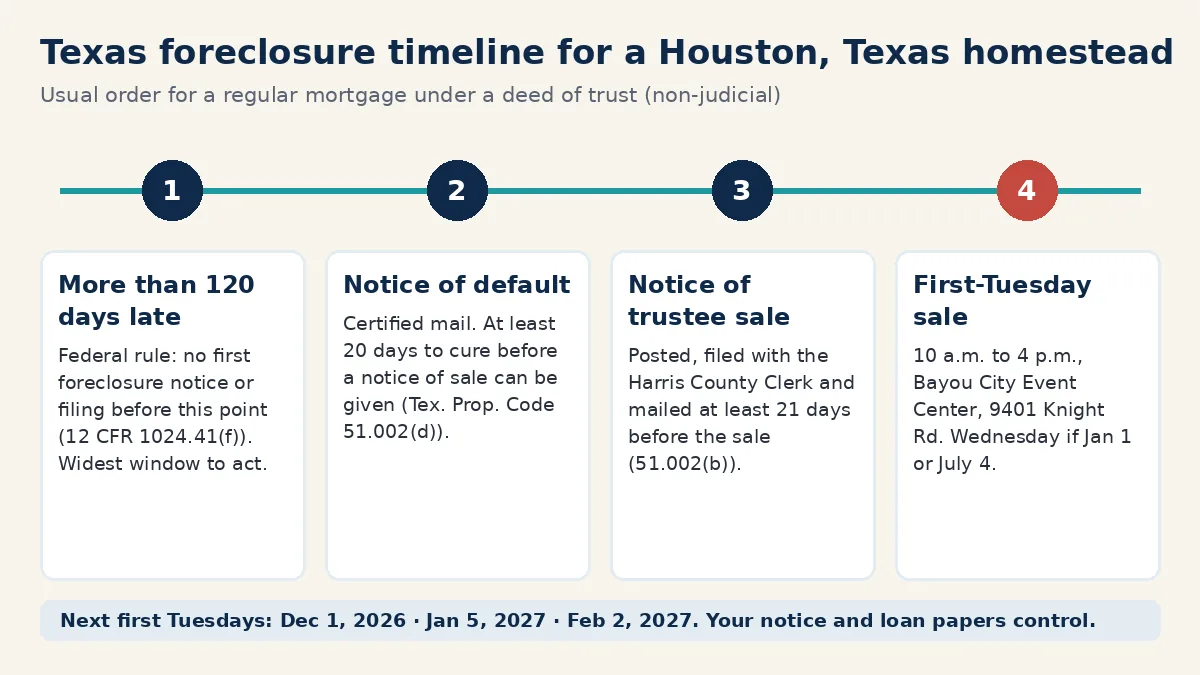
- Missed payments and servicer calls. Under federal servicing rules, the servicer generally can’t make the first notice or filing for foreclosure until your loan is more than 120 days delinquent (12 CFR 1024.41(f)). That’s your widest window, and the cheapest time to act.
- Notice of default and intent to accelerate. For a house you live in, Section 51.002(d) requires a certified-mail notice saying you’re in default and giving you at least 20 days to cure before a notice of sale can go out. If the letter says “opportunity to cure,” you’re here.
- Notice of trustee’s sale. At least 21 days before the auction, the notice must be posted at the courthouse, filed with the county clerk and sent to you by certified mail. It states the date, the earliest time the sale will begin and the substitute trustee’s name and address. If your letter says “Notice of Trustee’s Sale” or “Notice of Substitute Trustee’s Sale,” the clock is short.
- The sale. A public auction between 10 a.m. and 4 p.m. on the first Tuesday of the month, moved to Wednesday when that Tuesday is January 1 or July 4.
Run the math against real dates. The next first Tuesdays are December 1, 2026, January 5, 2027 and February 2, 2027. A December 1 sale needed its notice out around November 10. If you haven’t received a notice of sale yet, the earliest realistic sale is January 5, and that notice would have to go out by around mid-December. That doesn’t make January safe, but it may leave you a few weeks.
Where and when does a Harris County foreclosure sale actually happen?
Not on the downtown courthouse steps. The Harris County Clerk states that the auction is held on the first Tuesday of every month at the Bayou City Event Center, 9401 Knight Road, Houston, TX 77045, and that notices of trustee sale are filed and posted 21 days ahead at the Clerk’s office at 201 Caroline, 3rd floor, and on its website. Section 51.002(f-1) requires counties to post filed notices online with the date, time and location, so you can look up your own address and see whether it has been posted.
The Harris County Tax Office runs constable tax sales at the same venue on the same first Tuesdays. Houses in Fort Bend, Montgomery, Brazoria or Galveston County are sold in that county’s designated area, so trust the location on your notice.
Once a notice is filed, your address is public, so expect a wave of investor mail and texts. A section below covers how to tell legitimate buyers from the rest.
Is your debt a regular mortgage, a home equity loan, an HOA lien or a tax bill?
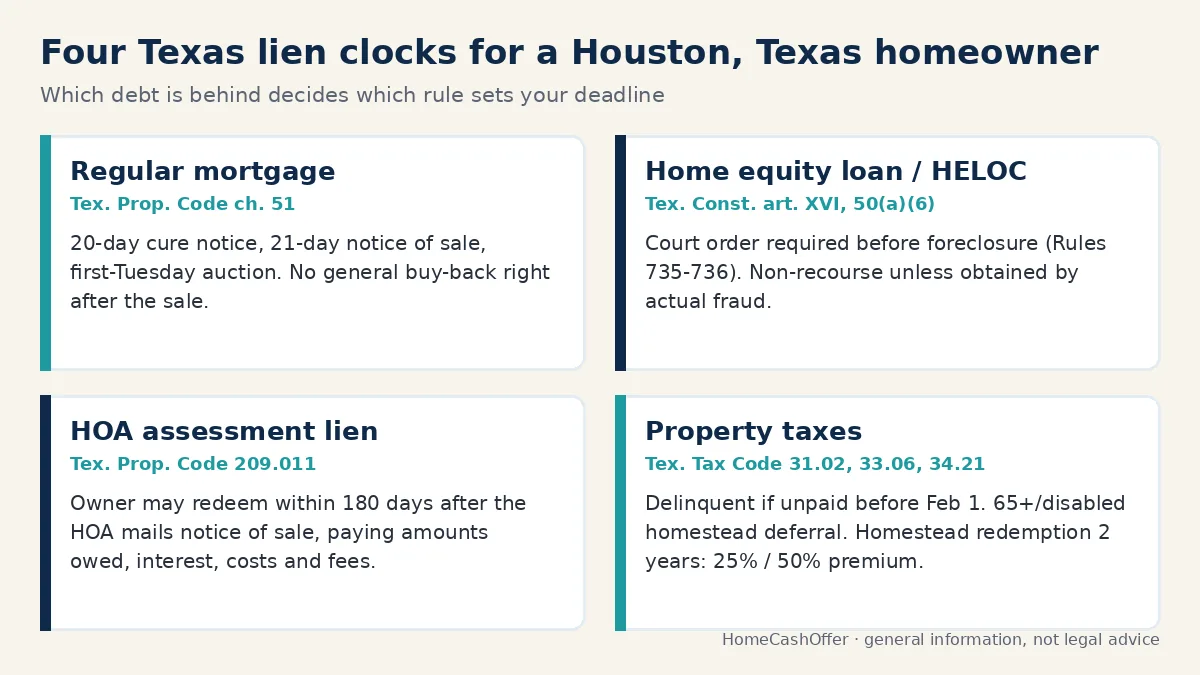
Each runs on its own Texas clock, and owners in suburban Harris County sometimes face more than one at once. Find yours in your closing papers or the letter’s heading:
- Regular purchase mortgage or refinance. Chapter 51 governs it: the 20-day cure notice, the 21-day notice of sale and the first-Tuesday auction. Texas has no general right to buy the house back after a mortgage trustee’s sale.
- Home equity loan or HELOC. The Texas Constitution, Article XVI, Section 50(a)(6) says these liens may be foreclosed only by court order, and that the loan is without personal recourse against the owner and spouse unless it was obtained by actual fraud. Lenders usually get it through the expedited process in Texas Rules of Civil Procedure 735 and 736, so court papers styled “In re: Order for Foreclosure” are your early warning. Don’t ignore them.
- HOA assessment lien. Many master-planned communities around Houston have one. After an HOA foreclosure, Property Code 209.011 lets the owner redeem within 180 days of the association’s notice of the sale, but only by paying what’s owed plus interest, costs and attorney’s fees.
- Property taxes. Texas taxes become delinquent if not paid before February 1 of the following year (Tax Code 31.02). Owners 65 or older, disabled owners and qualifying disabled veterans can defer taxes on a homestead they live in under Tax Code 33.06. A homestead sold at a tax sale can be redeemed for two years under Tax Code 34.21, with a 25% premium in the first year and 50% in the second. Many Houston mortgages escrow taxes, so an unpaid tax bill can also become a mortgage default.
Can you still sell after the notice of sale is posted?
Usually, yes, until the auction actually happens. What matters is the payoff, not the posting. A sale works if the price (or the price plus cash you bring to closing) covers the loan payoff, which will include arrears, late fees and foreclosure costs, along with any HOA balance, tax bill, second lien or judgment. A Houston title company orders the payoffs and wires the lender at closing.
A signed contract doesn’t cancel the auction by itself. Send the servicer the contract and a written request to postpone the sale so the closing can finish, preferably through a HUD-approved counselor or your attorney. Some servicers agree. They don’t have to.
A financed buyer struggles inside a 21-day window: appraisal, underwriting and, in much of Harris County, a flood zone determination and insurance quote all take time. You still owe the buyer an honest Texas seller’s disclosure, because the Property Code 5.008 exemption covers transfers made through a foreclosure sale, not a voluntary sale by the owner beforehand. Its flood questions cover present flood insurance, past water entry from a natural flood event, flooding from a reservoir release (a real issue for some west Houston homes near the Addicks and Barker reservoirs after Harvey in 2017), and whether the house sits in a 100-year floodplain, 500-year floodplain, floodway or reservoir flood pool.
What is the Houston market saying about your price right now?
It’s saying that listing takes time, so price that time into any plan with a deadline. Redfin’s Houston data for the three months ending October 2026 shows:
- a median sale price of $329,771, down 5.5% year over year
- a median of 54 days on market, compared with 49 a year earlier
- 35.7% of homes with price drops
- homes selling for about 96.5% of list price on average
On the buyer side, Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed rate at 7.28% as of November 19, 2026, up from 6.26% a year earlier. Higher rates mean fewer financed buyers can qualify at a given price. The same Redfin page cites First Street data estimating that 46% of Houston properties are at risk of severe flooding over the next 30 years, which feeds into what buyers pay for insurance.
Put together, a typical Houston listing spends close to two months on the market, still has to close after that, and a third of sellers cut their price along the way. That can work early in the 120-day window. Once the notice of sale is posted, it usually doesn’t.
What happens if the trustee sale goes through?
You lose the house, and in some cases the debt follows you. For a regular mortgage, Property Code 51.003 lets the lender sue for any deficiency within two years of the sale, and it lets you ask the court to credit the house’s fair market value if that was higher than the sale price. Home equity loans are non-recourse under Section 50(a)(6), as noted above, unless there was actual fraud.
Then comes possession. A former owner who stays in the house is often treated as a tenant at sufferance, and Property Code 24.005 allows as little as three days’ written notice to vacate before the new owner files an eviction suit. If you rent the house out, a tenant who is current on rent generally gets at least 30 days’ notice under the same section. Weigh that, plus the credit damage, against any sale price.
Who can help you keep the house instead of selling?
Start there if keeping the house is realistic:
- A HUD-approved housing counselor (HUD’s counselor search) can help you build a loss mitigation application and deal with your servicer.
- Lone Star Legal Aid, based in Houston, runs a Foreclosure Prevention Project for eligible homeowners.
- A Texas real estate or bankruptcy attorney can tell you whether the notices were done properly and whether a bankruptcy filing makes sense. A bankruptcy filing can stop a scheduled sale. A buyer can’t.
Timing matters because of a federal rule that interacts badly with Texas speed. Under 12 CFR 1024.41, if a servicer receives a complete loss mitigation application more than 37 days before a foreclosure sale, it must evaluate you within 30 days and generally can’t conduct the sale while the application is pending. A Texas notice of sale only has to come 21 days before the auction. If you wait for that notice to apply, you may already be inside the 37-day line. Send a complete application during the cure period.
Be wary of anyone who wants an upfront fee to “save” the house, asks you to deed it over while you pay them “rent,” or tells you to stop talking to your lender. A legitimate buyer closes through a title company and pays your loan off at closing.
From our deals
When Houston owners call us after a notice of sale, the price is rarely what decides whether a closing is possible. The unknown balances are: an HOA account that went to collections, a MUD or county tax bill the escrow didn’t cover, or a home improvement lien nobody mentioned. Owners who send the notice, a recent mortgage statement and the last tax bill on the first call get a straight answer quickly. Sometimes that answer is that a cash sale can’t clear everything before the first Tuesday, and we’d rather say so up front than sign a contract that can’t close.
When is a cash sale the wrong move?
A cash sale is the wrong move more often than investor ads admit:
- You have real equity and time. Early in the 120-day window, a well-priced listing usually nets more, even in a 54-day market.
- The hardship is over. If you’re back at work, a modification or repayment plan may keep the house. Try that first.
- You owe more than the house is worth. A cash buyer can’t pay more than the house is worth to cover a shortfall. A short sale or deed in lieu negotiated with the lender, ideally with an attorney’s help, may fit better. Check the deficiency rules above before signing anything.
- It’s a non-recourse home equity loan with little equity. The math changes because a deficiency judgment is off the table. Get legal advice before you trade equity for speed.
For a broader comparison of routes, including auctions, iBuyers and selling to family, see our guide to 12 ways to sell a house fast in Houston. For how Texas compares with judicial-foreclosure states, see the foreclosure timeline by state.
What does a HomeCashOffer sale look like on a first-Tuesday deadline?
It’s a written as-is offer and a title company closing, with an honest answer on whether it fits your date. HomeCashOffer has bought houses since 2013, in all 50 states, including Greater Houston. We don’t stop foreclosures, negotiate with your lender or give legal advice. Here’s what we do:
- Review your notice and lien picture, and tell you whether closing before the sale date is realistic.
- Make a written as-is offer (no repairs, cleanout or showings) to compare against a listing net and any loss mitigation offer.
- Open title with a Houston-area title company that orders the mortgage, HOA and tax payoffs.
- Close on your date, ahead of the auction if title allows, with the loan paid from the proceeds.
Related reading: our Austin water damage guide for storm-damaged Texas houses, the Houston probate guide if payments slipped on an inherited house, sell my house fast in Houston and Dallas for the wider metro, and our Texas page for statewide rules.
To get a written number while you still have options, request a cash offer or call HomeCashOffer at (405) 622-8705.
Sell your house fast in these markets
Local cash offer pages—or start with a nationwide request.
Frequently asked questions
How much notice does a Houston homeowner get before a foreclosure sale?+
For a home you live in, Texas Property Code 51.002(d) requires the mortgage servicer to send a certified-mail notice of default giving you at least 20 days to cure before a notice of sale can go out. The notice of sale then has to be posted, filed with the Harris County Clerk and mailed at least 21 days before the sale. Before any of that, federal servicing rules generally bar the first foreclosure notice or filing until the loan is more than 120 days delinquent.
Where are Harris County foreclosure auctions held?+
The Harris County Clerk says trustee sales are held on the first Tuesday of every month at the Bayou City Event Center, 9401 Knight Road, Houston, TX 77045, with notices filed and posted 21 days ahead at the Clerk's office at 201 Caroline and on the Clerk's website. Under Texas law the sale runs between 10 a.m. and 4 p.m., and it moves to Wednesday when the first Tuesday falls on January 1 or July 4. Fort Bend, Montgomery and other surrounding counties hold their own sales, so read the location printed on your notice.
Can I sell my Houston house after the notice of trustee sale is posted?+
Usually, yes, up until the sale actually happens, as long as the sale price (or the price plus cash you bring) pays off the loan and every other lien at closing. A signed contract does not cancel the auction by itself. Your title company will order a payoff, and you or your attorney should ask the servicer in writing whether it will postpone the sale to let a contracted closing finish. That decision is the lender's, not the buyer's.
Is foreclosure on a Texas home equity loan different from a regular mortgage?+
Yes. Under Article XVI, Section 50(a)(6) of the Texas Constitution, a home equity loan on a homestead can be foreclosed only by court order, which lenders usually seek through the expedited process in Texas Rules of Civil Procedure 735 and 736. The same section says the loan is without recourse for personal liability against the owner and spouse unless the loan was obtained by actual fraud. That changes both the timeline and the deficiency risk compared with a regular purchase mortgage.
If my HOA forecloses on my Houston-area house, can I get it back?+
Texas gives owners in a residential subdivision a redemption right after an HOA assessment-lien foreclosure. Under Property Code 209.011, you can redeem no later than the 180th day after the association mails written notice of the sale, by paying the amounts the statute lists, including the amounts owed, interest, the association's costs and attorney's fees. It is expensive, so dealing with the HOA balance before a sale is almost always cheaper.
Do I still have to fill out a Texas seller's disclosure if I sell before foreclosure?+
Generally, yes. Texas Property Code 5.008 exempts transfers made through a foreclosure sale or a court order, but an owner selling voluntarily before the auction is not making either of those transfers. The statutory form asks about flood insurance coverage, past flooding from a natural flood event or a reservoir release, and whether the house sits in a 100-year or 500-year floodplain, which matters for a lot of Harris County houses. A direct buyer may accept the house as-is, but you should still answer truthfully about what you know.
Can a cash buyer stop my Houston foreclosure?+
No buyer can stop a foreclosure, and HomeCashOffer does not claim to. What a sale can do is pay the loan off at a title company closing before the auction date if the numbers, the title and the calendar all work. Only your lender, a court or a bankruptcy filing can halt the sale itself. If you want to keep the house, talk to a HUD-approved housing counselor or a Texas attorney first.
Ready to see what a cash offer looks like?
No repairs required. No agent commissions when you sell to us. No obligation to accept.
Request your no-obligation cash offer
Prefer a dedicated form? Visit Get a Cash Offer Today.
Get My Cash Offer
Share your name, phone, and property address. No obligation. We will follow up shortly.