Las Vegas foreclosure data, 2026: what the Clark County numbers show, and seven ways out compared
By HomeCashOffer Team · Published · County data through September 2026; market data through October 2026
Short answer: Foreclosures are rising in Las Vegas from a low base. ATTOM ranked Nevada first among states for foreclosure rate in July 2026 (one filing for every 1,703 housing units) and the Las Vegas metro third among large metros (one in every 1,394). In Clark County, 1,561 notices of default were recorded from March through September 2026, yet 64% of trustee sales that reached a final outcome were cancelled rather than sold, which usually means the owner caught up, modified, sold or otherwise settled first. Nevada's statutory clock gives an owner at least three months after a notice of default before the sale can be noticed, so most owners with equity have time to compare reinstatement, mediation, a listing and a cash sale if they start early.
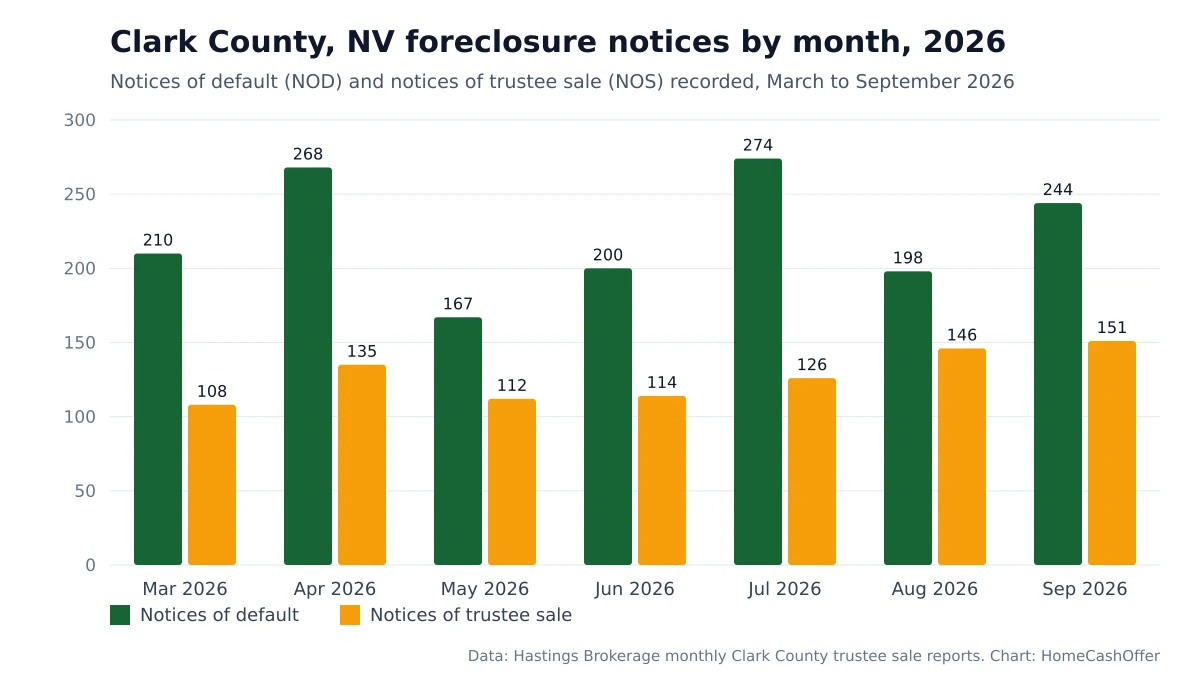
Clark County foreclosure notices and trustee sale results, March to September 2026
"NOD" is a notice of default and election to sell; "NOS" is a notice of trustee sale. The last four columns are what happened to trustee sales on the calendar that month. Source: Hastings Brokerage monthly Clark County trustee sale reports, a Las Vegas brokerage that tracks recorded notices and sale results; it does not publish a detailed method, so treat the counts as a consistent local tracker rather than an official county statistic. Scroll sideways on a phone.
| Month | Notices of default | Notices of sale | Sales cancelled | Sales postponed | Sold to a third party | Went back to the lender |
|---|---|---|---|---|---|---|
| Mar 2026 | 210 | 108 | 123 | 125 | 37 | 25 |
| Apr 2026 | 268 | 135 | 133 | 135 | 28 | 23 |
| May 2026 | 167 | 112 | 130 | 153 | 57 | 39 |
| Jun 2026 | 200 | 114 | 117 | 144 | 31 | 36 |
| Jul 2026 | 274 | 126 | 135 | 160 | 29 | 39 |
| Aug 2026 | 198 | 146 | 114 | 134 | 39 | 33 |
| Sep 2026 | 244 | 151 | 116 | 189 | 30 | 45 |
| 7-month total | 1,561 | 892 | 868 | 1,040 | 251 | 240 |
Stats dated: monthly reports for March to September 2026, the September edition posted October 9, 2026; retrieved November 10, 2026. Totals and percentages are our arithmetic. A postponed sale can be counted again in a later month.
What the county numbers actually say
Most scheduled sales never happen. Across the seven months, 868 trustee sales were cancelled and 491 were completed, so about 64% of sales that reached a final result ended in a cancellation. A cancellation is not always good news for the owner, but it usually means the loan was reinstated or modified, the house was sold first, or the case was resolved some other way. Only about one notice of default in three made it to a completed sale in the same window (491 sales against 1,561 notices, a rough comparison because the cases overlap in time).
Postponements are the norm, not the exception. There were more postponements (1,040) than cancellations, and September had the most of any month at 189. A postponement buys time, but it is the lender's decision, and it should never be the plan.
When a sale does go ahead, investors take about half. Of the 491 completed sales, 251 (51%) went to a third-party bidder and 240 reverted to the lender. Bidders at a trustee sale usually pay cash and often cannot inspect inside, so they bid with a discount, and the owner has no right to buy the house back afterwards (NRS 107.080(5)). Selling before the sale date is how an owner controls the price.
The pipeline is filling. Notices of sale rose from 108 in March to 151 in September, and September's 244 notices of default were the second-highest month in the table after July's 274. Owners who received a notice of default this summer are the ones whose sale dates are landing this winter.
How Las Vegas compares nationally
- July 2026: Nevada had the highest state foreclosure rate in the country, one filing for every 1,703 housing units, with 779 properties with filings, up 47% from June and 39% from July 2025. The Las Vegas metro ranked third among metros of 200,000 or more at one in every 1,394 housing units, behind Punta Gorda, Florida and Killeen, Texas (ATTOM, July 2026;state table). The national rate was one in 3,603.
- August 2026: Nevada slipped to second (one in 1,920) behind South Carolina (ATTOM, August 2026), and Las Vegas-Henderson-Paradise ranked eighth among large metros at one in 1,584, as reported from ATTOM's metro table (Daily Mail).
- First half of 2026: 2,935 Nevada properties had a foreclosure filing, 0.22% of housing units (one in 452), the sixth-worst state rate and up 6% from a year earlier (ATTOM midyear report).
- How long Nevada cases last: homes foreclosed in Nevada in the second quarter of 2026 had spent an average of 1,507 days in the process, the fifth-longest of any state; the U.S. average was 563 days (ATTOM). That average is pulled up by old, stalled cases. It does not mean you have four years; the statute allows a sale in months.
For context, distressed sales are still a small share of normal home sales. Short sales and foreclosures were 1.1% of existing-home sales through the Las Vegas REALTORS MLS in October 2026, up from 0.9% a year earlier, and 1.1% in September, up from 0.5% (LVR, October 2026; LVR, September 2026).
The Nevada foreclosure clock, step by step
Statutory minimums for a residential deed of trust under NRS Chapter 107 and NRS 40.455. Real cases often take longer; your own notices control.
| Step | Timing | Statute |
|---|---|---|
| Pre-foreclosure notice from the servicer | At least 30 days after the missed payment and at least 30 days before a notice of default is recorded | NRS 107.500, 107.510 |
| Notice of default and election to sell recorded and mailed | Starts the cure period: 35 days by default, and for owner-occupied homes the right to catch up runs until 5 days before the sale | NRS 107.080(2)-(3), 107.0805 |
| Mediation decision | Within 30 days after the notice of default is served: petition the district court ($25) or waive | NRS 107.086(3) |
| Notice of default posted on the house | No later than 100 days before the sale date | NRS 107.087 |
| Notice of trustee sale | Only after at least 3 months have passed since the notice of default was recorded; posted 20 days and published once a week for 3 weeks; posted on the house 15 days before the sale | NRS 107.080(2)(d), 107.080(4), 107.087 |
| Payoff statement | The lender must send a payoff statement within 21 days of a proper request; ask the day you decide to sell | NRS 107.210 |
| Trustee sale | Title passes to the buyer with no right of redemption | NRS 107.080(5) |
| Deficiency claim | Lender must apply within 6 months after the sale; barred for many original purchase-money loans from financial institutions on a single-family home the owner lived in and never refinanced | NRS 40.455 |
Adding up the floors (our arithmetic): 30 days before the pre-foreclosure notice can go out, 30 more before the notice of default, three months before the sale can be noticed and about three weeks of notice puts the earliest possible sale roughly five and a half to six months after the first missed payment.
Seven ways out of a Las Vegas foreclosure, compared
Method: each option is compared on how long it takes under Nevada law or current market data, what you keep, what it costs, who it fits and the main risk. Listing times use Redfin's Las Vegas median days on market plus a 30-to-45-day financed closing, which is our estimate. Other ranges describe how each route usually works; they are not survey data.
| Option | How long it takes | What you keep | What it costs | Best fit | Main risk |
|---|---|---|---|---|---|
| Reinstate (pay what is past due) | Owner-occupied homes: until 5 days before the sale date (NRS 107.0805) | The house and the loan | Arrears plus fees and costs in the reinstatement quote | A short, fixed setback that is now over | Needs a lump sum; falling behind again restarts the process |
| Loan modification through Nevada foreclosure mediation | Petition within 30 days after the notice of default is served; the case then runs on the court's calendar (NRS 107.086) | The house, on new loan terms if approved | $25 petition fee plus your share of the mediation fee | Owner-occupants whose income can carry a modified payment | The servicer does not have to approve a modification |
| List with an agent and close before the sale | Las Vegas median of 55 days to go under contract (Redfin, Sep 2026), plus roughly 30 to 45 days to close with a financed buyer | Your equity, less commission and closing costs | Commission, repairs a buyer asks for, holding costs | Clean, updated homes with clear equity and three months or more of runway | 40.5% of Las Vegas listings had a price drop in Sep 2026; a slow month can push you past the sale date |
| Direct as-is cash sale | Often 7 to 30 days once the payoff and title are clear | Your equity, less the buyer's discount for condition and speed | Lower price than a fixed-up retail sale; few or no repairs or commissions | Dated, damaged, vacant, inherited or rented homes, or a sale date that is close | Price is below retail; compare more than one written offer |
| Short sale | Unpredictable; the lender must approve the price and terms | Usually no cash to the seller | Credit impact; possible deficiency unless the lender waives it in writing | Owing more than the house will sell for | Approval can take longer than the time left before the sale |
| Deed in lieu of foreclosure | Depends on the servicer's review | Nothing; you hand the house back | Credit impact; get any deficiency waiver in writing | No equity, no wish to keep the home, and a cooperative servicer | The servicer may ask you to try a short sale first, and second loans or HOA liens can complicate it |
| Let the trustee sale happen | At least 3 months after the notice of default, plus 20+ days of sale notice (NRS 107.080) | Nothing unless the sale brings more than is owed | Credit impact; possible deficiency claim filed within 6 months (NRS 40.455) | Rarely the best choice if there is equity | No right of redemption after a Nevada trustee sale (NRS 107.080(5)) |
Equity decides which option makes sense
The single most useful number is the gap between what you owe in total (loan balance, arrears, fees, HOA balance, property taxes) and what the house would really sell for. For a reference point, Southern Nevada's median existing single-family price was $475,000 in October 2026, down from the $490,000 record set in May and June, and the condo and townhome median was $279,000 (Las Vegas REALTORS). Within the City of Las Vegas, Redfin put the median sale price at $449,786 for the three months ending September 2026, with homes taking a median 55 days to go under contract and 40.5% of listings taking a price cut (Redfin).
The market has more choice for buyers than a year ago. Las Vegas REALTORS counted 8,112 single-family homes for sale without an offer at the end of October 2026, up 7.6% from a year earlier, and the sales pace equaled nearly six months of supply, up from just over four and a half months. That matters if you are on a deadline: a listing priced a little high can sit through your sale date.
- Clear equity and three or more months left: get an agent's pricing opinion and at least one as-is cash offer, and compare the net to you, not the headline price.
- Equity but little time, or a house that needs work: a direct cash sale that closes before the sale date usually protects more of your equity than letting the trustee sale run.
- Little or no equity: talk to your servicer and a HUD-approved counselor about modification, a short sale or a deed in lieu. A cash buyer cannot pay more than the house is worth to solve a negative-equity problem.
The Las Vegas twist: your HOA can foreclose too
Much of the Las Vegas Valley is master-planned, and Nevada gives associations real teeth. An HOA's lien for up to nine months of regular assessments, plus capped collection costs, ranks ahead of the first mortgage (NRS 116.3116). Those costs are capped at $165 for a demand letter, $325 for a notice of delinquent assessment, $90 for an intent-to-record letter, $400 for a notice of default and $400 for a trustee's sale guaranty.
The association's path to a sale under NRS 116.31162 is:
- No earlier than 60 days after the debt is past due, it sends a fee schedule, a proposed repayment plan and notice of your right to a hearing before the board. You have 30 days to pay, sign up for the plan or ask for a hearing.
- It mails a notice of delinquent assessment.
- At least 30 days later it records a notice of default and election to sell, which must carry a bold warning that you could lose your home.
- You then have 90 days to pay the lien before a sale can follow.
An association generally cannot foreclose over fines alone unless the violation threatens health or safety. If you are behind on both the mortgage and the HOA, the HOA balance comes out of any sale first, so get a payoff from the association as well as the lender.
If you got a notice of default this month: a 10-day plan
- Day 1: find the recording date on the notice of default and count three months forward. That is the earliest point the sale can be noticed. Mark the 30-day mediation deadline too.
- Day 1 to 2: request a written reinstatement quote and a payoff statement from the servicer; under NRS 107.210 the lender has 21 days to send the payoff.
- Day 2 to 5: call a HUD-approved housing counselor (HUD counselor finder) and decide whether to petition for mediation or waive it.
- Day 3 to 7: ask your HOA for a ledger and the Clark County Treasurer for any unpaid taxes, so you know the full payoff.
- Day 5 to 10: get an agent's pricing opinion and one or two written as-is cash offers, and compare the net from each against reinstating or modifying.
The full 50-state picture, including how Nevada compares with California and Arizona, is in our foreclosure timeline by state.
Las Vegas foreclosure FAQs
How many foreclosures are there in Las Vegas right now?
In Clark County, 1,561 notices of default and 892 notices of trustee sale were recorded from March through September 2026, according to Hastings Brokerage's monthly trustee sale reports; September alone had 244 notices of default and 151 notices of sale. ATTOM ranked the Las Vegas metro third among large metros for foreclosure rate in July 2026 (one filing per 1,394 housing units). Distressed sales are still a small slice of the market: short sales and foreclosures were 1.1% of Las Vegas REALTORS MLS sales in October 2026.
How long does foreclosure take in Nevada?
The statutory floor is short. After the servicer's 30-day pre-foreclosure notice, the notice of default is recorded, and the sale cannot be noticed until at least three months later, followed by at least 20 days of posted notice and three weeks of newspaper publication (NRS 107.080). In practice cases often run far longer: ATTOM found that Nevada homes foreclosed in the second quarter of 2026 had been in the process for an average of 1,507 days, the fifth-longest in the country. Do not plan around the average; plan around the dates on your own notices.
Can I sell my Las Vegas house after a notice of default?
Yes. You still own the house until the trustee sale, and a sale that closes first lets escrow pay off the loan, the arrears and the fees from the proceeds, and you keep any equity left. Order a payoff statement right away (the lender has 21 days to send it under NRS 107.210), and tell any buyer the sale date so the closing is scheduled ahead of it. HomeCashOffer cannot stop a foreclosure or promise a postponement.
What is Nevada foreclosure mediation and is it worth it?
For owner-occupied homes, the notice of default must come with a form to petition the district court for mediation with someone who has authority to modify the loan. You must file within 30 days after the notice is served and pay a $25 fee plus your share of the mediator's fee (NRS 107.086). It is worth it if you want to keep the house and your income can support a modified payment. It is not a guarantee: the servicer does not have to agree.
Can my HOA foreclose on my house in Las Vegas?
Yes. Nevada associations can foreclose their assessment lien, and up to nine months of regular assessments plus capped collection costs ranks ahead of a first mortgage (NRS 116.3116). The association must first send a past-due notice with a repayment plan and hearing rights no earlier than 60 days after the debt is past due, then a notice of delinquent assessment, then record a notice of default at least 30 days later, and then wait 90 days for payment (NRS 116.31162). It generally cannot foreclose over fines alone.
Will I owe money after a Las Vegas foreclosure?
Possibly. A lender has six months after a Nevada foreclosure sale to apply for a deficiency judgment, and the court holds a hearing on fair market value first (NRS 40.455 and 40.457). A financial-institution lender cannot get one if the loan bought a single-family home, you lived in it continuously, you owned it at the sale and you never refinanced. Ask a Nevada attorney how this applies to your loan.
Does HomeCashOffer buy Las Vegas houses in foreclosure?
Yes. HomeCashOffer buys Las Vegas, North Las Vegas and Henderson houses as-is for cash, including homes with a recorded notice of default, HOA liens or missed payments, and closes through a Nevada title company that pays the lender from the sale. It does not give legal advice or stop foreclosures, and it does not keep a Las Vegas office. Call (405) 622-8705 or request a written offer online.
Sources and method
County figures come from Hastings Brokerage's monthly Clark County trustee sale reports for March through September 2026. Statewide and metro rates come from ATTOM's monthly and midyear foreclosure reports; the August metro ranking is ATTOM data as reported by the Daily Mail. Market figures come from Las Vegas REALTORS (MLS sales, September and October 2026) and Redfin (City of Las Vegas, three months ending September 2026). Every source was checked on November 10, 2026. Totals and shares labeled as our arithmetic are calculated from those figures. HomeCashOffer is a cash home buyer and one of the options described, so we have a stake in the comparison; we have not invented any prices, offer percentages or outcomes.
- Hastings Brokerage, Ltd.: Clark County, NV trustee sale report, September 2026 (with March-August comparisons)
- Hastings Brokerage, Ltd.: Clark County, NV trustee sale report, August 2026
- ATTOM: July 2026 U.S. Foreclosure Market Report (released Aug. 27, 2026)
- ATTOM: Foreclosure activity by state, July 2026 (PDF)
- ATTOM: August 2026 U.S. Foreclosure Market Report (released Sept. 17, 2026)
- Daily Mail (Sept. 2026), reporting ATTOM August 2026 metro rankings
- ATTOM: Midyear 2026 U.S. Foreclosure Market Report (released July 16, 2026)
- Las Vegas REALTORS: housing statistics for October 2026 (released Nov. 6, 2026)
- Las Vegas REALTORS: housing statistics for September 2026 (released Oct. 6, 2026)
- Redfin: Las Vegas, NV housing market (three months ending September 2026)
- NRS Chapter 107: deeds of trust and trustee sales (107.080, 107.0805, 107.086, 107.087, 107.210, 107.500, 107.510)
- NRS Chapter 40: deficiency judgments (40.455, 40.457)
- NRS Chapter 116: HOA assessment liens and foreclosure (116.3116, 116.31162)
- HUD: find a housing counselor
Want a cash number to set against your sale date?
HomeCashOffer buys houses as-is across Las Vegas, North Las Vegas, Henderson and the rest of Clark County, including homes with a notice of default or an HOA lien. Get a written, no-obligation offer and compare it with reinstating, modifying or listing.
Related: Sell my house fast in Las Vegas · North Las Vegas · Henderson · Las Vegas cash home buyers compared · Selling with code violations in Las Vegas